The agreement is subject to approval by IMF management

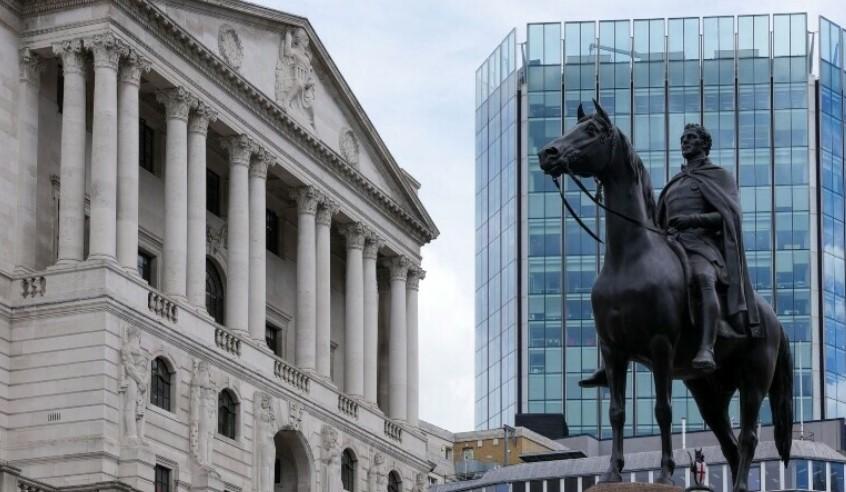
Colombo: Crisis-hit Sri Lanka has reached a preliminary agreement with the International Monetary Fund (IMF) for a loan of about $2.9 billion, the international lender said in a statement on Thursday.
"The objectives of Sri Lanka's new Fund-supported programme are to restore macroeconomic stability and debt sustainability," the statement said, outlining the 48-month long arrangement under the IMF's Extended Fund Facility.
The agreement is subject to approval by IMF management and its executive board and is contingent on Sri Lankan authorities following through with previously agreed measures.
The IMF also requires receiving financing assurances from Sri Lanka's official creditors, besides ensuring efforts are made to reach a collaborative agreement with private creditors.
"Debt relief from Sri Lanka's creditors and additional financing from multilateral partners will be required to help ensure debt sustainability and close financing gaps," the statement added.
The IMF programme will aim to raise government revenue to support fiscal consolidation, introduce new pricing for fuel and electricity, hike social spending, bolster central bank autonomy and rebuild the country's depleted foreign reserves.
"Starting from one of the lowest revenue levels in the world, the programme will implement major tax reforms. These reforms include making the personal income tax more progressive and broadening the tax base for corporate income tax and VAT," the statement said.
Sri Lanka needs to restructure nearly $30 billion of debt, and Japan has offered to lead talks with the other main creditors, including India and China.
It will also need to strike a deal with international banks and asset managers that hold the majority of its $19 billion worth of sovereign bonds, which are now classified as in default.
The debt-laden country has been seeking up to $3 billion from the IMF in a bid to escape its worst economic crisis since independence from Britain in 1948.
Sri Lankans have faced acute shortages of fuel and other basic goods for months, leaving it in political turmoil and hit by runaway inflation, which is now at almost 65% year on year.
SOURCE: Reuters
The Xbox Nano has a hidden cloud secret
- 12 hours ago
Delhi world's most polluted major city on eve of Diwali, Swiss group says
- a day ago
Adobe’s Premiere mobile app is adding licensed music from ‘leading artists’
- 12 hours ago
Supreme Court dismisses Punjab appeals against police promotions
- 20 hours ago
AI scams are everywhere — and they’re slick. Here’s how to protect yourself and your family.
- a day ago
The midterms were a youth revolt
- a day ago
Pakistan, Sudan sign visa-free travel agreement for official, diplomatic passport holders
- a day ago
India says landed heavy-lift military aircraft at highest altitude
- 21 hours ago
The moment Donald Trump blew the midterms
- a day ago
Rahm Emanuel knows how congressional Democrats can keep winning
- a day ago
Australia's Khawaja disputes findings in 2018 ball-tampering investigation
- a day ago
Google’s Pixel 11 phones are up to 27 percent off
- 3 hours ago